procurement budget planning
Procurement budget planning gives an organization a clear view of the money, timing and approvals needed before a purchase moves forward. It connects a defined need with available funding, a suitable procurement approach and a record of the decisions made.
Key Takeaways
- A strong procurement budget answers three questions early: how much money is available, when it can be spent, and who needs to approve the purchase.
- Connecting each purchase to a documented need helps teams spend public funds responsibly and with confidence.
- Confirming funding before choosing a procurement approach makes it easier to select the right process for the purchase.
- Keeping a clear record of budget decisions supports transparency and simplifies future reviews or audits.
- Planning the budget early in the process helps organizations avoid delays caused by missing approvals or unexpected costs.
What procurement budget planning means in plain terms
Procurement budget planning means estimating the full cost of a planned purchase, confirming that funds are available and aligning the purchase with organizational priorities. It brings procurement, program, finance and approval teams together before a commitment is made.
A simple, plain-language definition
Planning starts with a defined need. The team describes what it may purchase, when it is needed and which costs could continue after the initial order. Those costs may include implementation, maintenance, training, renewals, shipping, taxes, staff time or contract administration. The estimate should identify its assumptions, known information and unanswered questions.
The team then connects the need to an approved funding source and spending authority. It can review timing, requirements, market information, risk, contract length and the procurement method that fits the situation. Early planning does not guarantee a particular outcome. It creates a documented basis for responsible decisions.
Why budget planning supports accountability and transparency
A well-organized budget record shows why a purchase is needed, who reviewed it and how the proposed spending supports organizational objectives. It also helps decision-makers consider competing priorities, affordability and operational risk. A traceable record supports responsible stewardship of public funds and clearer handoffs between teams.
For newcomers, procurement budget planning is a practical way to build confidence. A careful estimate, recorded rationale and understood approval route make later conversations easier. Teams seeking a common foundation can explore Procurement Training for Teams, which supports shared public-sector procurement knowledge.
Where procurement budget planning fits in the procurement lifecycle
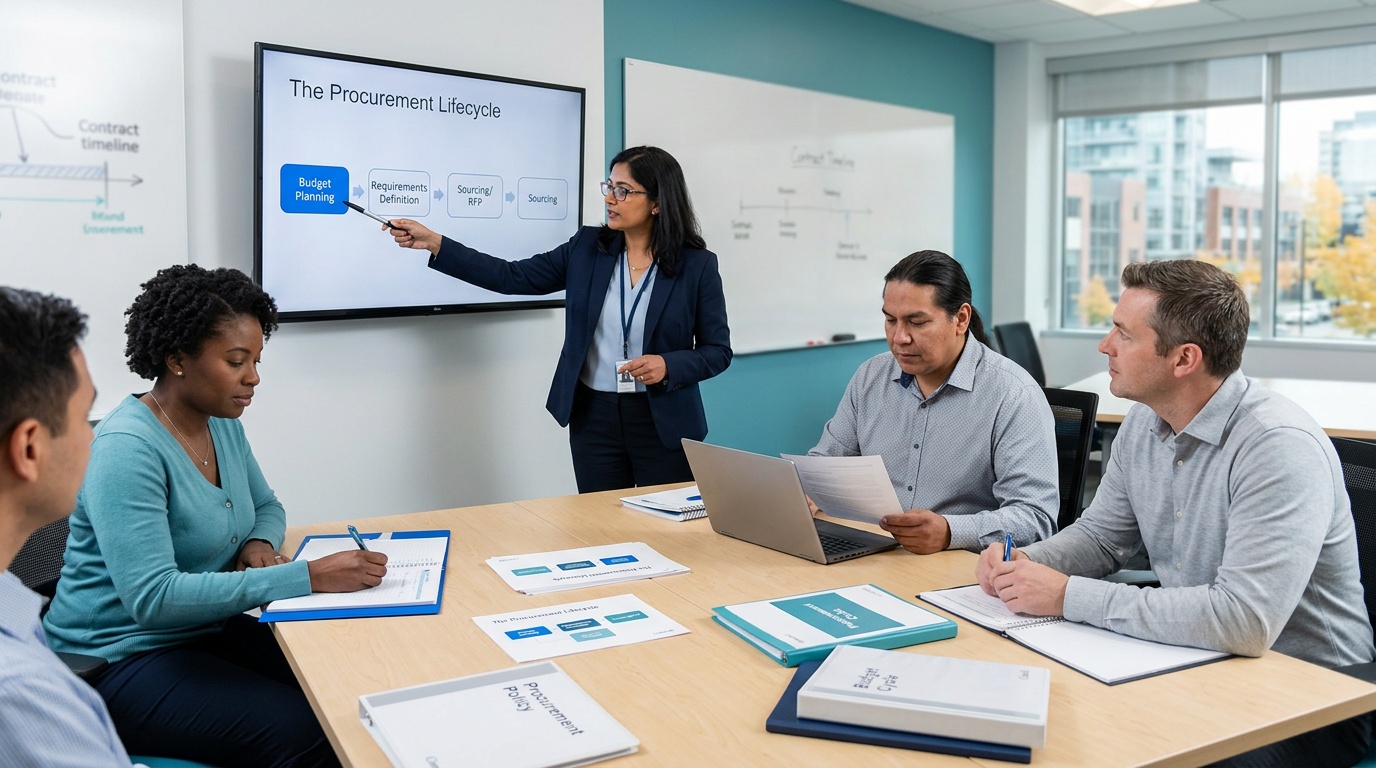
The procurement lifecycle at a glance
Budget planning sits near the beginning of the procurement lifecycle, before a requirement goes to the market. The following model shows how the stages connect:
- Planning: define the need, expected outcomes, funding, timing and requirements.
- Sourcing: choose an approach, prepare documents and invite potential suppliers where appropriate.
- Contracting: evaluate according to the stated process, obtain approvals and establish the agreement.
- Managing: monitor deliverables, payments, performance, changes, risks and communication.
- Closeout: confirm completion, resolve outstanding matters, retain records and capture lessons learned.
This is a teaching framework, not a replacement for organizational policy. Processes may combine stages or require additional reviews. A request for proposal, often called an RFP, is one possible sourcing document, not a universal answer.
Why early budget conversations shape better outcomes
Early discussions can reveal whether the requirement is ready, whether the timing is realistic and whether the scope matches available funding. They can also identify stakeholders, approval points, service levels, supplier considerations and contract-management responsibilities before documents are drafted.
That preparation informs the solicitation, evaluation plan, contract terms and delivery schedule. Estimates may need review when scope, timing or risk changes, so budget planning continues throughout the lifecycle. Teams that want consistent terminology can consider Procurement Training for Teams. Organizations seeking help with procurement processes and planning controls can also explore procurement consulting services.
A starter checklist for procurement budget planning
Questions to ask before planning begins
Bring the following questions into one conversation before a request moves forward: What is being purchased, and which business or public-service need does it address? When is it required? Who will use it, manage it and approve the spending? Which funding source applies? Is it a one-time purchase or an ongoing service?
- Need: Is the outcome clear enough to describe?
- Timing: Are key dates, dependencies and lead times known?
- Funding: Has the appropriate budget owner confirmed available funds?
- Authority: Which person or group must review and approve the commitment?
- Risk: Could privacy, security, accessibility, continuity or supplier capacity affect the estimate?
- Contract: What costs and responsibilities may continue after award?
Documentation habits that hold up later
Record the estimate, date, assumptions, source information and unresolved questions. Keep the business need, scope notes, funding confirmation, approvals and material changes together in an accessible record. A short decision log can explain changes to timing or scope and identify follow-up actions. Consistent file names and named responsibilities help finance, procurement, program and audit participants work from the same reference. Teams that need planning documents can use procurement templates to support consistent recordkeeping.
A hypothetical example, clearly labelled
Hypothetical teaching scenario: A small purchasing team is preparing for a new operational service. One person describes the need, another confirms the funding source and a program lead identifies the required start date. The team records recurring costs, approval points and questions for potential suppliers before selecting a procurement approach. The estimate is updated as the scope and delivery information become clearer.
Teams in municipalities and agencies benefit from a shared budget vocabulary. Agree on terms such as funding source, commitment, forecast, recurring cost, approval authority, contingency and contract owner. Shared language reduces assumptions and helps each participant understand the decision they must support.
How budgets differ across federal, provincial and municipal procurement
Jurisdictional differences at a high level
Public procurement practices vary across federal, provincial, territorial, regional and municipal organizations. The planning group, approval route, financial cycle, delegation rules, reporting expectations and procedures may differ. Federal organizations work within their applicable federal framework; provincial and territorial organizations follow their government’s framework; municipalities and regional authorities apply local policies and procedures.
| Setting | Typical planning focus | Where requirements may be established |
|---|---|---|
| Federal | Departmental priorities, authorities, funding approvals and federal procurement procedures | Government-wide and departmental policies, directives and official procurement guidance |
| Provincial or territorial | Ministry or agency priorities, appropriations, delegations and applicable public-sector procedures | Provincial or territorial legislation, policy instruments and procurement services |
| Municipal or regional | Approved budgets, council direction, local services, delegations and operating requirements | Bylaws, purchasing policies, administrative procedures and official local guidance |
Where to find official Canadian guidance
Start with your organization’s purchasing policy, financial controls, delegation schedule and records requirements. Then consult the relevant official government source. Federal readers can begin with Public Services and Procurement Canada. Provincial, territorial, regional and municipal readers should use the procurement service or authority published by their own government. The Treasury Board of Canada Secretariat policy directory provides federal policy context, not a replacement for local direction.
Building budget-planning confidence: pitfalls and practical next steps
Common pitfalls newcomers can avoid
A vague estimate may hide delivery, implementation or renewal costs. An unclear approval path can delay a purchase and make accountability harder to follow. Missing notes leave new team members without the context behind an earlier decision. The practical response is to name assumptions, confirm authority and record the information supporting the estimate. Perfect information is not required at the outset; an honest record and a plan for validation are.
A do-and-avoid approach for stronger planning
Pros
- Use plain descriptions for the need, expected outcome and cost assumptions.
- Confirm approval roles before commitments or supplier discussions advance.
- Keep dated records of changes, reviews, decisions and follow-up actions.
- Discuss total ownership cost, operational impact and contract-management capacity.
Cons
- Do not treat an early estimate as final without checking its basis.
- Do not rely on informal approvals that cannot be located later.
- Do not assume that one team’s terminology has the same meaning for finance or program staff.
How foundational training builds a shared planning vocabulary
Foundational learning gives people a common way to discuss requirements, forecasts, commitments, authority, risk, scope and supplier performance. That shared vocabulary supports handoffs between program staff, procurement professionals, finance teams and contract managers. It also creates room to discuss ethical conduct, fairness, transparency, documentation and sustainable public purchasing without assigning blame when a gap appears.
Where NECI The Procurement School Inc. fits in
NECI The Procurement School Inc. offers Canadian-focused public sector procurement education for individuals and teams. The Public Sector Procurement Program provides a progressive certification pathway from essentials to procurement expert level. Municipalities and agencies seeking a common learning experience can consider Procurement Training for Teams. The program.
Start with one clear requirement, one accountable approval path and one reliable record. Careful preparation helps teams procure with confidence.
Frequently Asked Questions
What are the 5 P's of procurement?
The 5 P’s of procurement are commonly described as people, process, price, product and performance, a simple framework for checking that a planned purchase is well supported. Many teams also recall the phrase ‘proper planning prevents poor performance.’ Procurement budget planning brings these pieces together early, before any commitment is made.
What are the 5 R's of procurement?
The 5 R’s of procurement mean securing the right quality, in the right quantity, at the right price, from the right source, at the right time. Careful budget planning helps a team test each of these conditions early, when funding, timing and requirements can still be adjusted with confidence.
What are the 7 steps of procurement?
The 7 steps of procurement typically move from need identification and requisition review through solicitation, evaluation, award, contract management and final payment or closeout. Budget planning belongs at the very first step in public procurement, because a documented estimate and confirmed funding make every later stage easier to explain and defend.
What are the 7 principles of procurement?
The 7 principles of procurement usually include transparency, fairness, open competition, value for money, accountability, integrity and efficiency. A well-kept budget record supports several of these at once by showing why a purchase is needed, who reviewed it and how the proposed spending fits organizational priorities.
What is the 70-10-10-10 budget rule?
The 70-10-10-10 rule is a personal budgeting guideline that assigns 70 percent of income to living expenses, 10 percent to savings, 10 percent to investing or giving, and 10 percent to debt. Public procurement budgets use different structures, though the shared lesson is deliberate allocation: every planned dollar needs a confirmed home before a purchase moves forward.
What costs should a procurement budget include?
A procurement budget should include the complete cost of a purchase: implementation, maintenance, training, renewals, shipping, taxes, staff time and contract administration, not just the initial order price. Confirming whether the requirement is a one-time buy or an ongoing service also keeps the estimate realistic and easier to defend.
Who should be involved in procurement budget planning?
Procurement budget planning works best when procurement, program, finance and approval teams take part together, since each group holds a piece of the funding, timing and risk picture. The budget owner confirms available funds, while a named approver reviews the commitment before any purchase moves ahead.